When Did Tax on Social Security Benefits Start?
Curious about when the tax on Social Security benefits began? In this article, we dive into the history and evolution of this tax, explaining how it came into play and how it affects today’s retirees.
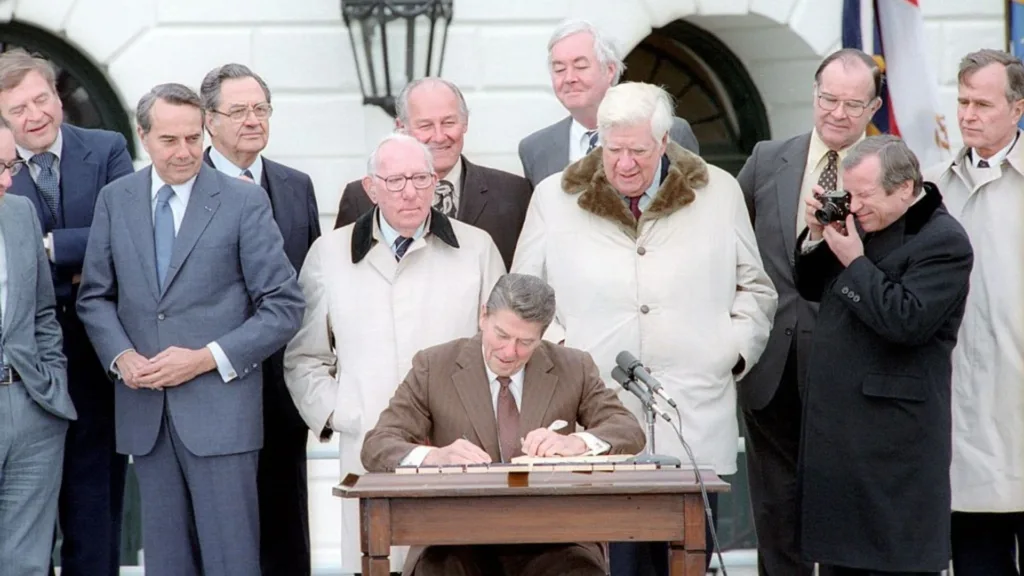
If you’re wondering when did tax on Social Security benefits start, you’re not alone! The history of taxation on Social Security benefits is a fascinating one, with its origins in the 1980s. In 1984, a major shift occurred when Social Security benefits became subject to federal income tax for the first time under the Social Security Amendments of 1983. Prior to this, Social Security benefits were not taxed, meaning that retirees could rely on them without worrying about additional tax burdens. However, this change was introduced as part of a broader effort to shore up the finances of the Social Security system, which was facing potential future shortfalls. Initially, only a portion of benefits could be taxed, and it was based on the beneficiary’s overall income. The tax rate and thresholds evolved over time, and in 1993, under the Clinton administration, the taxation of Social Security benefits expanded even further, with up to 85% of benefits becoming taxable for higher-income individuals. This shift has had a significant impact on retirees’ tax obligations, and understanding when did tax on Social Security benefits start is crucial for anyone planning their retirement finances. In this article, we’ll explore how and why Social Security benefits became taxable and what it means for individuals receiving these benefits today.
Why Were Social Security Benefits Taxed?
Before 1984, Social Security benefits were considered untouchable by the IRS. But by the early 1980s, the government was facing serious financial challenges, and the Social Security system itself was projected to face future funding shortages. In response, the Social Security Amendments of 1983 introduced the taxation of Social Security benefits as a way to raise additional revenue for the program. The idea was that individuals with higher incomes could afford to pay taxes on their benefits, especially those whose Social Security benefits made up only a portion of their overall income.
The introduction of the tax on Social Security benefits was a significant policy change, as it was the first time Social Security checks were subject to taxation at the federal level. Initially, up to 50% of Social Security benefits could be taxed for individuals whose income exceeded a certain threshold. The decision to implement this tax reflected broader shifts in U.S. tax policy and aimed to strike a balance between ensuring the financial stability of Social Security and providing financial support to retirees.
How Did the Tax on Social Security Benefits Evolve?
The tax on Social Security benefits didn’t stop with the 1984 amendments. In 1993, President Bill Clinton’s administration introduced another round of changes, expanding the taxation to a higher percentage of benefits. Under the Omnibus Budget Reconciliation Act of 1993, the tax rate on Social Security benefits was increased, and now, up to 85% of benefits could be taxed for higher-income recipients.
This adjustment affected those individuals with substantial income from other sources, such as pensions, earnings from employment, or interest and dividends. By expanding the scope of Social Security benefit taxation, the government aimed to generate more revenue and address the continued funding concerns surrounding the program. This move was controversial at the time, as many argued that taxing benefits for people who had already paid into the system would create an additional financial burden for retirees.
Who Is Affected by the Tax on Social Security Benefits?
The introduction and evolution of the tax on Social Security benefits have had the most significant impact on retirees with higher income levels. Initially, the tax only affected individuals whose combined income (including Social Security benefits, pensions, and other taxable income) exceeded certain thresholds. Today, if your income exceeds the limits set by the IRS, a portion of your Social Security benefits could be subject to federal tax.
For single filers, if their combined income exceeds $25,000, they may be taxed on up to 50% of their Social Security benefits. For married couples filing jointly, the threshold is $32,000. When combined income exceeds $34,000 for single filers or $44,000 for married couples, up to 85% of Social Security benefits may be taxed. These thresholds and percentages can vary slightly based on changes to tax laws, but they are essential for understanding how much of your Social Security benefits may be taxed.
How Does the Tax on Social Security Benefits Affect Retirement Planning?
The tax on Social Security benefits has added a layer of complexity to retirement planning. Many retirees did not anticipate that a portion of their Social Security benefits would be taxed, and this can lead to an unexpected tax burden. Understanding the thresholds and how your overall income affects your Social Security taxability is key to effective retirement planning.
For those who are close to or already in retirement, it’s essential to consider how additional sources of income, like pensions, investment earnings, or part-time work, could push them into a higher tax bracket. Proper tax planning can help minimize the impact of Social Security taxation, and strategies like tax-deferred accounts (e.g., IRAs) or tax-free municipal bonds may help reduce taxable income in retirement.
Conclusion
The question when did tax on Social Security benefits start points to a critical turning point in U.S. tax policy, particularly for retirees. The tax on Social Security benefits began in 1984 as part of the Social Security Amendments of 1983 and was expanded in 1993 under President Clinton’s administration. Understanding when this tax started and how it evolved is essential for anyone planning their retirement, as it helps determine how much of their Social Security income will be taxed. With the right tax strategies in place, retirees can minimize the impact of this tax and ensure they’re financially prepared for their golden years.
Frequently Asked Questions
- When did tax on Social Security benefits start?
Tax on Social Security benefits began in 1984 under the Social Security Amendments of 1983. - How much of Social Security benefits are taxed?
Depending on your income, up to 50% of Social Security benefits can be taxed, and this can rise to 85% for high-income individuals. - How can I reduce the tax burden on my Social Security benefits?
Strategies like minimizing additional taxable income, using tax-deferred accounts, or considering tax-free investments can help reduce the tax on your Social Security benefits.